
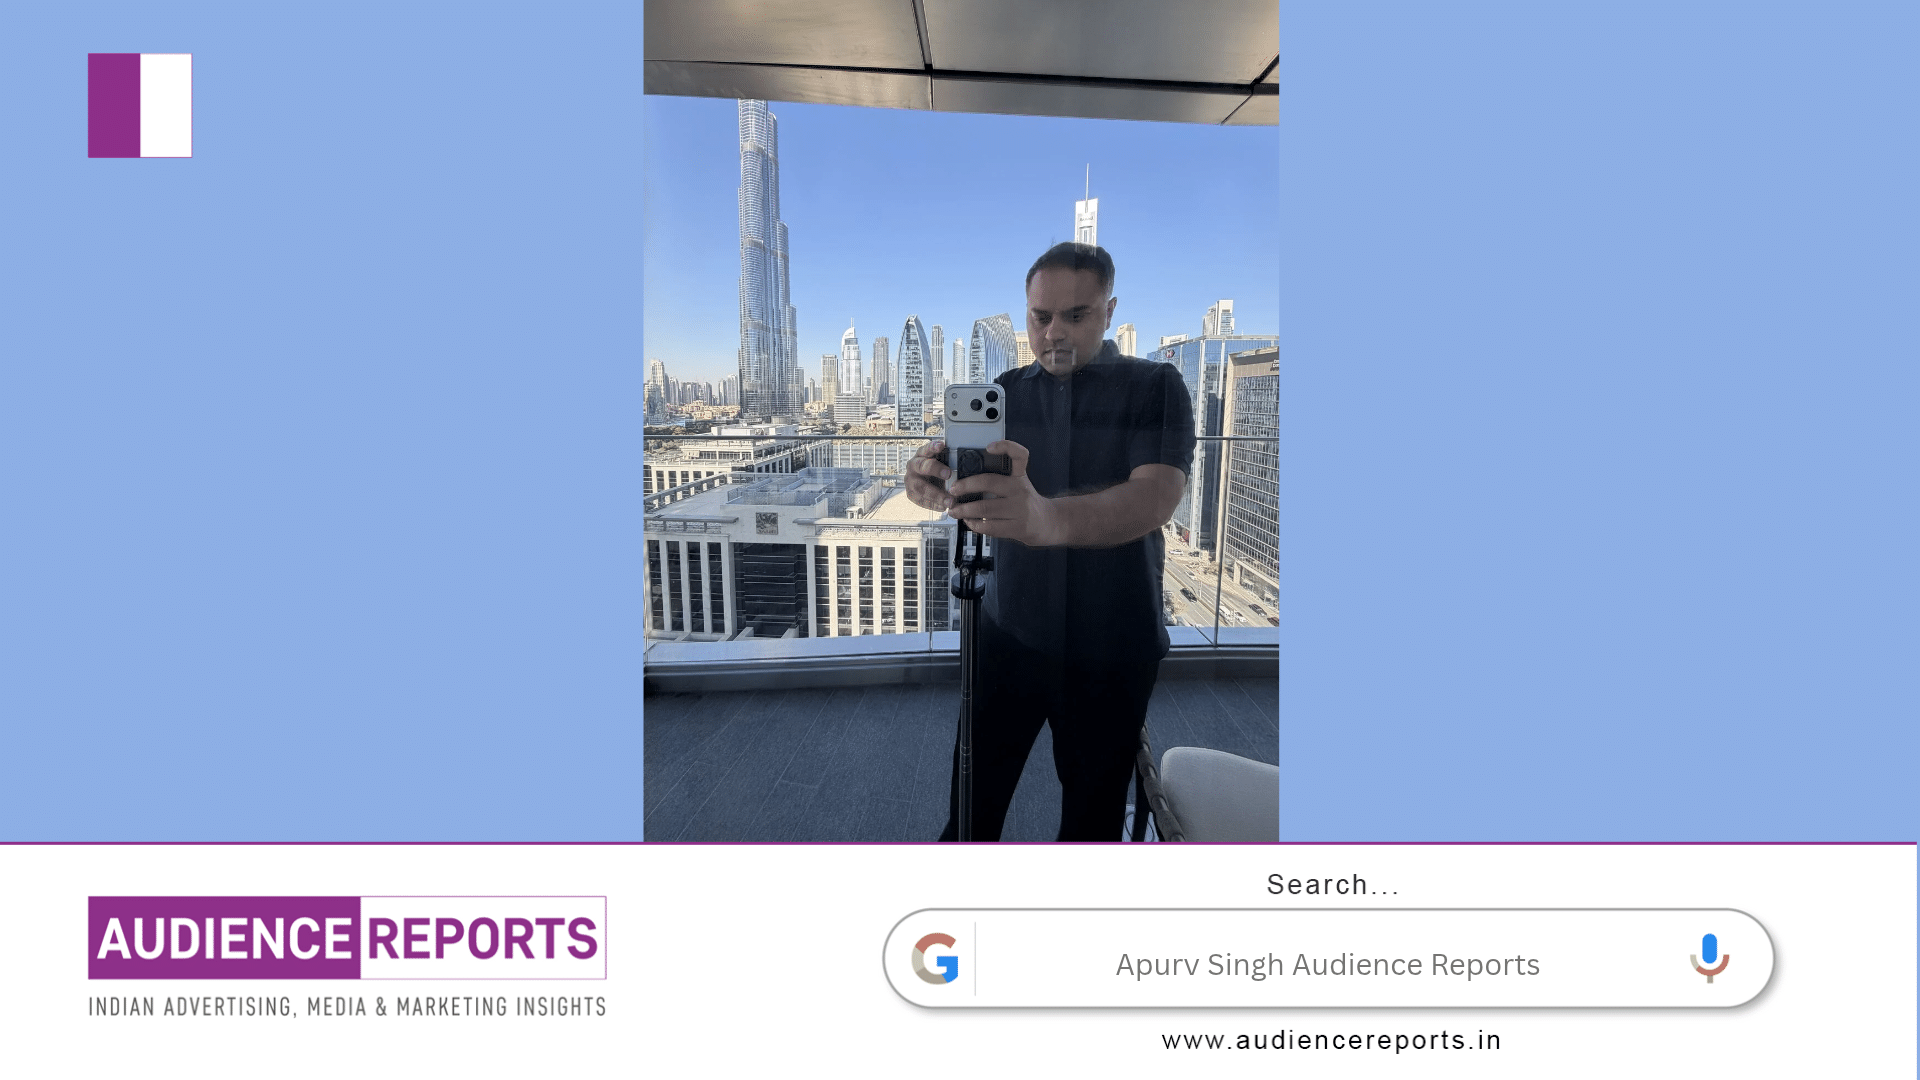
Apurv Singh, Founder of HQ Digital, demonstrates that making a major life decision requires more than ambition. It requires preparation, financial discipline, and a clear understanding of the responsibilities that come with change. In his second part of the Life After Corporate series, Apurv Singh shares how he prepared financially for his family’s move to Dubai over a period of 15 months. His approach highlights an important lesson: successful transitions are often planned long before they become visible to others.
Moving to another country can be exciting, but the financial responsibilities behind that decision are often underestimated. Relocation involves housing, visas, daily expenses, business operations, and legal compliance. Apurv Singh understood that moving his family without sufficient preparation could create unnecessary pressure. Therefore, he decided to build financial stability in the UAE before making the actual move.
Planning the Move Before Taking the First Step
In August 2025, Apurv Singh established a company in the UAE and began billing his international clients through it. At the same time, his Indian company continued serving domestic clients and managing his education business. This arrangement allowed him to maintain operations in both markets while preparing for a different chapter of life.
For the following 15 months, Apurv Singh retained almost 90% of the earnings generated through the UAE business in its company account. He avoided transferring those funds to India or withdrawing them into his personal UAE account.
This decision was connected to a larger financial objective. He wanted to accumulate enough capital within the UAE business before relocating his family. Instead of depending on immediate income after arrival, he wanted a financial foundation already in place.
The approach reflects an important principle for entrepreneurs: preparation should begin before the actual transition. Waiting until a major expense arrives to arrange the necessary funds can create pressure that could have been avoided through advance planning.
Understanding Tax Responsibilities and Legal Compliance
Financial planning becomes more complicated when business activities extend across international borders. Different countries have different taxation systems, residency requirements, and compliance obligations.
Apurv Singh spent considerable time understanding the tax laws of India and the UAE, particularly India’s Place of Effective Management (POEM) rules. These rules can have significant implications for foreign companies when their key management and commercial decisions are effectively made in India.
He also considered how personal withdrawals could create separate tax implications depending on his residential status and the manner in which money was received.
Rather than searching for shortcuts, Apurv Singh focused on understanding the legal and financial responsibilities involved. He kept company funds separate and considered the compliance requirements before making decisions.
This is an important lesson for business owners expanding internationally. Establishing a company in another country does not automatically eliminate obligations in the country where the business is managed or where its owners have tax connections.
Apurv Singh’s experience highlights why professional guidance and careful documentation matter when managing businesses across borders. Financial decisions should be based on applicable laws rather than assumptions or incomplete information.
Deciding How Much Money Is Enough
One of the most practical parts of Apurv Singh’s financial preparation was determining how much savings would be necessary before moving.
He used a simple example. If his family’s estimated monthly expenses in Dubai were represented by ₹100, his initial savings target was ₹300. This amount would cover approximately three months of living expenses, with additional funds required for visas, rental deposits, and relocation costs.
However, his business performed better than expected. Instead of reaching the original target of ₹300, Apurv Singh accumulated ₹800.
The difference between the initial target and the final savings demonstrates the importance of having a financial goal while remaining prepared for changing circumstances.
His experience also shows that savings targets should be connected to actual expenses. A relocation budget should not focus only on monthly household spending. It must also account for one-time costs, unexpected expenses, and the financial requirements of establishing a new home.
For anyone planning an international move, calculating these expenses in advance can help replace uncertainty with a more realistic financial plan.
Savings Alone Cannot Guarantee Financial Stability
Another important consideration in Apurv Singh’s plan was cash flow.
Having substantial savings can provide temporary security, but savings alone cannot sustain a lifestyle indefinitely. A business owner must also understand whether existing operations can generate enough recurring income to cover monthly expenses.
Apurv Singh wanted to ensure that his businesses could continue generating sufficient revenue without requiring him to constantly use accumulated savings.
He also did not want to depend on acquiring new clients immediately after relocating. Finding new customers takes time, and building business relationships in a new market can involve uncertainty.
This distinction between savings and cash flow is essential. Savings provide a financial cushion, while consistent income supports long-term sustainability.
Apurv Singh’s approach reflects a broader business lesson: entrepreneurs should evaluate the strength of their existing revenue systems before taking major personal or professional decisions. A business that depends entirely on the owner’s immediate involvement may face difficulties when circumstances change.
Building reliable operations before relocating can reduce the pressure associated with starting again in a different environment.
Preparing for the Responsibilities of a New Country
Apurv Singh also considered his time outside India as part of his tax-residency planning. Spending more than six months outside India during a year can be relevant, but Indian tax residency is determined by specific statutory tests and exceptions, not simply a universal six-month rule.
His decision to arrange the Dubai home through the UAE company’s lease was another part of his preparation. Since he would also be working from that location, he recognized the importance of appropriately accounting for personal and business expenses.
These details demonstrate that relocation involves several interconnected decisions. Housing, business arrangements, tax residency, income generation, and personal finances cannot always be treated as completely separate matters.
Apurv Singh’s experience illustrates why entrepreneurs need to examine the wider implications of their decisions before implementing them.
The Value of Preparing Before Change Happens
Perhaps the most meaningful aspect of Apurv Singh’s story is that he did not present his approach as a perfect formula. He acknowledged that nobody handed him a complete playbook. Instead, he learned through research, planning, and evaluating the financial and legal implications of his choices.
His objective was straightforward: he did not want to move his family to another country and then begin worrying about how to finance their everyday lives.
That mindset offers a valuable lesson beyond international relocation. Whether someone is changing careers, starting a company, moving cities, or entering a new industry, preparation can make uncertainty easier to manage.
Apurv Singh shows that financial independence is not simply about earning more money. It also involves controlling expenses, understanding obligations, maintaining reserves, and building income systems that can support future decisions.
For entrepreneurs, the ability to plan beyond immediate business performance is particularly important. Revenue growth matters, but so does knowing how much money can be retained, how operations will continue, and what risks may emerge when personal circumstances change.
Conclusion: Make Preparation Part of the Journey
Apurv Singh’s financial planning for his Dubai relocation offers a practical perspective on managing major life transitions. His 15-month preparation period involved building UAE business capital, understanding cross-border tax considerations, establishing savings targets, evaluating cash flow, and arranging housing before moving his family.
The central lesson is that important decisions should not depend entirely on optimism. They need financial preparation and a realistic understanding of potential challenges.
Apurv Singh’s journey reminds aspiring entrepreneurs and professionals that moving forward does not always mean taking immediate action. Sometimes, the most productive step is spending time preparing for what comes next.
A successful transition is not defined only by reaching a new destination. It is also defined by how responsibly someone prepares for life after arriving there.
The strongest moves are often made possible by the preparation that happens long before the move itself.